Home & Personal Insurance
You've built your business carefully. Your home, your boat, and everything inside them deserve the same attention. We bring the independent, multi-carrier approach we use for commercial clients to the personal coverage Texas families depend on.
Personal coverage reviewed by an advisor, not a call center
Most people buy homeowners insurance when they close on a house and never look at it again. Then a kitchen fire or a burst pipe shows them what their policy actually says.
Many of our clients are business owners who first came to us for commercial coverage and then asked us to look at their home. We start the same way we do with a business. We find out what you own and what you have in place today, and then we shop your coverage across our carrier relationships. You get one advisor who knows your whole picture.
Personal coverage has gotten more complicated. Rebuilding costs have climbed, many carriers have changed how they pay roof claims, and flood is never included in a homeowners or condo policy. We explain all of it before you have a claim.
Actual policy language governs all claims. All coverages are subject to policy terms, conditions, and underwriting approval. Speak with a licensed advisor for guidance specific to your property.
What we cover
Click any coverage line to learn how it works, what it covers, and what to watch for in Texas.
Homeowners
Coverage for your dwelling, other structures, belongings, and personal liability. We make sure your home is insured to today's rebuild cost and that you know what you'd pay out of pocket on a claim.
Learn moreCondominium (HO-6)
Your association's master policy stops somewhere, and your HO-6 has to pick up from there. We read your HOA documents so your coverage covers what the master policy doesn't, including loss assessments.
Learn moreFlood
Homeowners and condo policies exclude flood. We compare National Flood Insurance Program (NFIP) and private flood options, including for homes outside high-risk zones.
Learn moreBoat & Watercraft
From bass boats and pontoons to offshore center consoles and jet skis. Coverage for physical damage, liability, towing, and the gear aboard, whether you run on Texas lakes or the Gulf.
Learn morePersonal Umbrella
Extra liability protection above your home, auto, and boat policies. One serious accident or lawsuit can exceed your underlying limits; an umbrella protects your savings and future income.
Learn moreFor Business Owners
Already a commercial or benefits client? Your advisor can review your personal coverage alongside your business program. One relationship, one point of contact.
See commercial coverageTexas homes face risks most national websites don't explain
Some Texas homeowners discover gaps in their coverage only after a claim. These are the issues we walk every client through:
- ✓ Foundations and clay soils: Texas soils shift, and most policies exclude settling and cracking. We explain what is and isn't covered when foundation damage happens.
- ✓ Roof coverage: many carriers now pay older roofs at actual cash value or on a depreciation schedule. We check how yours is covered before you need to file a claim.
- ✓ Flood: flood always needs a separate policy, and homes outside high-risk zones flood too. We compare NFIP and private options side by side.
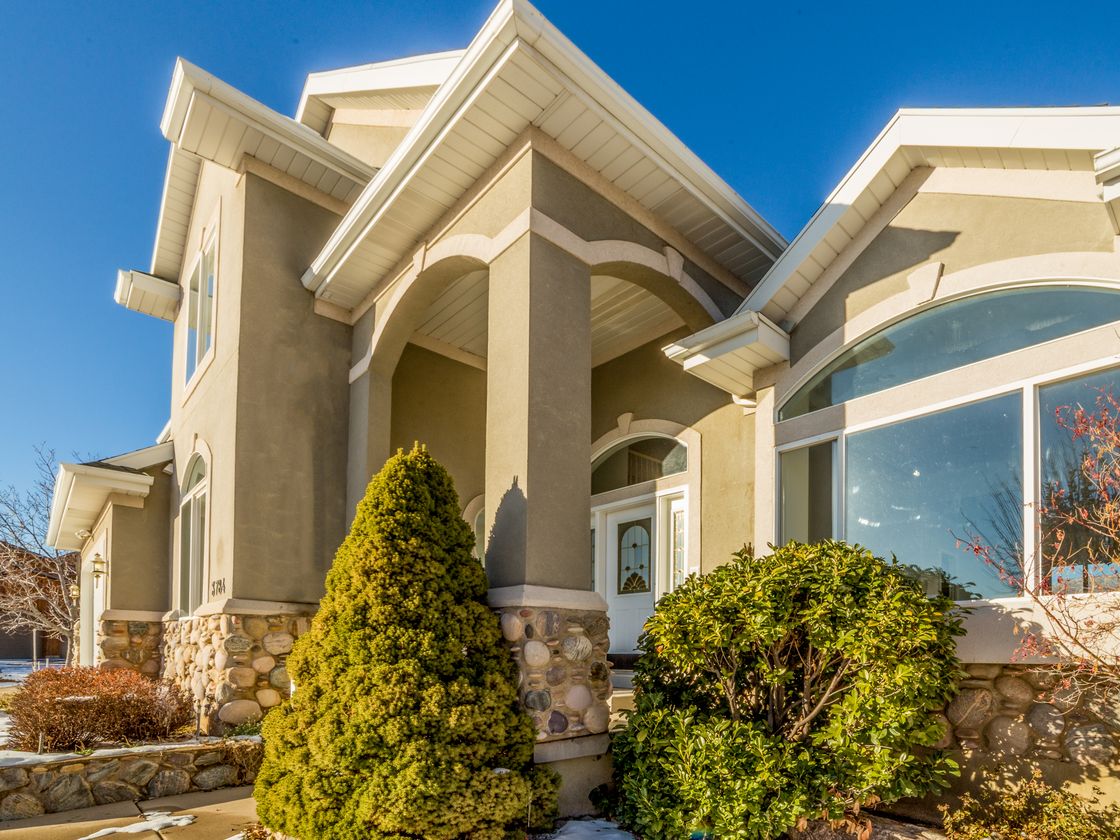
Get a no-cost review of your personal coverage
Tell us about your home, condo, boat, or liability coverage and we'll review your current policies, identify gaps, and present options. No obligation, no pressure.
Coverage descriptions on this page are general in nature and for educational purposes only. Actual policy language governs all claims. NFIP rules are subject to change. Verify current program eligibility and requirements. All coverages are subject to policy terms, conditions, and underwriting approval.